Business Strategy
Break-Even Analysis for Small Businesses: Know the Sales You Need to Stop Losing Money
By ATTPL Consultancy Marketplace Editorial Team · · 2 min read
A simple guide to break-even analysis — fixed and variable costs, contribution margin, a worked example, and how to use the numbers for pricing, hiring and expansion decisions.
Why break-even matters
Every business owner should know one number by heart: the sales needed each month just to cover costs. That is the break-even point. Below it, you lose money; above it, every sale adds to profit. Knowing it makes pricing, hiring and expansion decisions far clearer.
Fixed and variable costs
Fixed costs stay roughly the same whatever you sell — rent, salaries of permanent staff, loan EMIs, software subscriptions. Variable costs move with each unit sold — raw material, packing, sales commission, delivery. Some costs are partly fixed and partly variable, such as electricity; split them sensibly.
The formula and a worked example
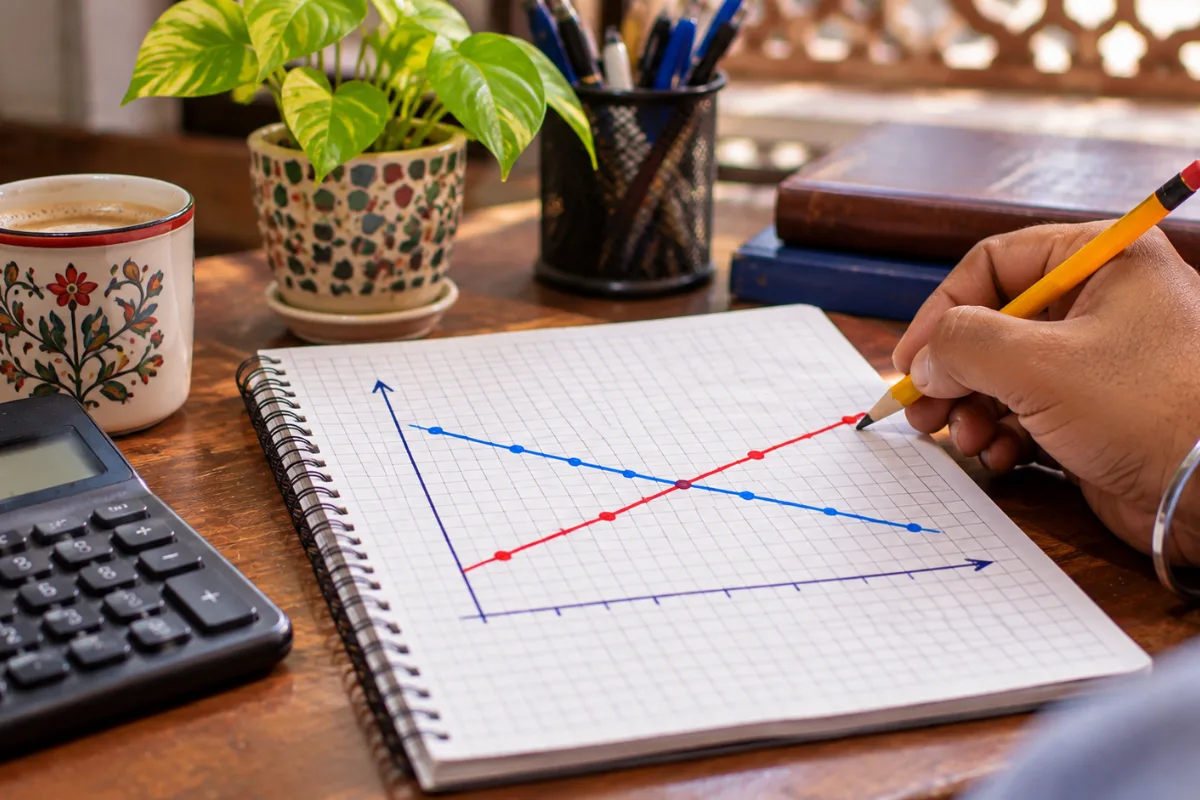
Contribution per unit = selling price − variable cost per unit. Break-even units = fixed costs ÷ contribution per unit.
Example (illustrative): a workshop has monthly fixed costs of ₹1,50,000. It sells a product for ₹500, and the variable cost is ₹300. Contribution is ₹200 per unit, so break-even is 1,50,000 ÷ 200 = 750 units a month, or ₹3,75,000 of sales. If it sells 900 units, the extra 150 units add ₹30,000 profit.
Using break-even for decisions
- Pricing: see how a discount raises the units you must sell
- Hiring: check how many extra sales a new salary requires
- Rent or expansion: test the impact of higher fixed costs before committing
- Product mix: focus on items with higher contribution
Our guide on pricing strategy for small businesses explains how to set prices that protect margin.
Margin of safety
Margin of safety is how far actual sales are above break-even. In the example, selling 900 units gives a margin of safety of 150 units, about 17 percent. A thin margin means even a small drop in sales can push the business into loss, so build buffers in cash and costs.
Keep it updated
Costs change, so recalculate break-even every quarter or when prices, rent or salaries change. Put it on your monthly dashboard alongside cash flow. ATTPL Consultancy helps small businesses with costing and financial planning, and equipment funding options are explained in our partner guide on machinery and equipment loans for MSMEs. Group-level advisory is available from ATTPL HOLDCO.
Frequently asked questions
What is the break-even point?
It is the level of sales at which total revenue equals total costs, so the business makes neither profit nor loss.
How do you calculate break-even units?
Divide fixed costs by contribution per unit, where contribution is selling price minus variable cost per unit.
How often should break-even be recalculated?
At least every quarter, and whenever prices or major costs change.
Sources and further reading
This article is general business information, not financial, tax or legal advice. Consult a qualified professional for your situation.